No Gas at Circle K Again
Y'all're never too young to kickoff saving for retirement. Today, people live much longer, and many older adults run out of retirement savings.
There are several unlike types of retirement savings accounts, and 401(k) plans are some of the nigh common ones. If your employer offers a 401(k), you'd be wise to learn nigh the benefits of these retirement accounts.
Section 401(grand) of the U.s. tax code makes information technology possible for employees to maintain 401(g) accounts. That's where these fiscal tools become their odd name. A 401(k) is a retirement savings account. Twelvemonth after year, employees deposit a portion of their income into the account. So, a fiscal establishment invests that money.
Different 401(g) plans may have different investment standards. Often, 401(g) monies are invested in mutual funds. Although investment earnings are never guaranteed, the strategic investment of this money by a professional unremarkably results in a 401(k) account becoming far more valuable than the total money deposited. This money earns more than interest through investment than in a traditional savings account.
How Does a 401(thou) Programme Work?
For a traditional 401(thousand) plan, employees choose how much money each pay period volition become towards their 401(k). The amount appears on their pay stub as a deduction, and the deduction comes out of the employee's gross income before taxes.
In many companies, employers concord to match 401(k) contributions. Some employers match 100% of what employees contribute. This means that if you contribute $l per paycheck to your 401(k), your company will contribute an boosted $l to your 401(k). Other employers simply requite a flat dollar amount to each employees' 401(chiliad) account each year. Still, other businesses practise non make any contributions.
All the money the employee has contributed to the 401(yard) throughout the yr qualifies as a tax deduction at tax time. You pay taxes on the coin when you withdraw your contributed income from a traditional 401(one thousand) plan.
With a Roth 401(m), contributions come from your net pay subsequently taxes accept already been deducted from your gross income. This takes intendance of your income revenue enhancement obligation. The contributions do not authorize every bit a tax deduction, and there are no additional taxes to pay when you withdraw the coin at retirement age. Roth 401(g) plans are far less common than traditional ones.
What Are the Rules for a 401(thousand)?
There are annual contribution limits for 401(k) plans. Each employee tin only contribute up to $20,500 to their 401(thou) in a year. For an employee who receives a monthly paycheck, that averages to only over $1,700 per cheque. Contributions made past the employer are not included in this limit, but the sum of employer and employee contributions cannot exceed $61,000 for a single year.
Employees aged 50 and older can contribute more than to their 401(k) each year. These additional contributions are called take hold of-up contributions, and they are allowed because these employees are closer to retirement age, making their saving needs fifty-fifty more immediate. Older employees tin can contribute $6,500 over the usual limit each twelvemonth. These boosted contributions are still payroll deductions. Among employers who match employee contributions, some will non match grab-upwards contributions.
Since a 401(k) plan is a retirement account, the intention is that you will non withdraw any of the money before you retire. However, the money belongs to y'all, and then you practise have the option of withdrawing early. If you are 59.5 or older when yous make a withdrawal, there are no penalties. If yous are younger than retirement age, any amount that you withdraw from your 401(k) counts every bit income for that tax twelvemonth, then yous will pay income taxes on the money. There is also a 10% penalty for early withdraw. If you have $10,000 out of your 401(k) when you are 40, you will pay $1,000 in penalties, and you will also owe income taxes on the coin.
How Much Should You Save for Your 401(k)
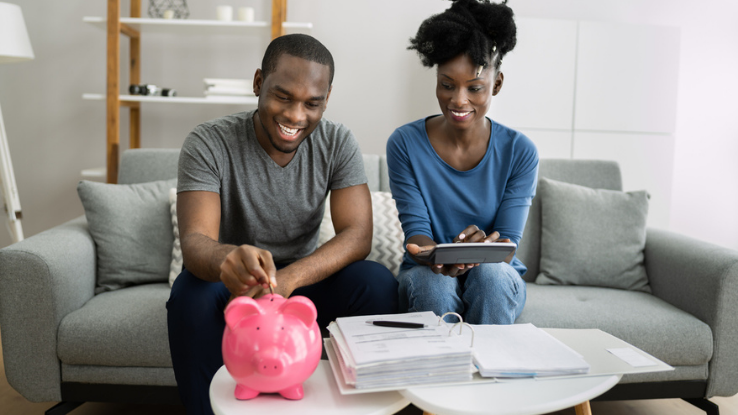
There are a few cardinal factors to consider when deciding how much to salvage in your 401(k). Remember that 401(k) contributions are deductions from your paycheck. It certainly does not brand sense to make significant 401(k) contributions while falling behind on monthly bills. Carefully consider your monthly budget to determine how much of your pay you can go without.
Balance your need to relieve for retirement with the current demand to have plenty money in an accessible savings account for financial emergencies. A 401(k) is a retirement savings account. The intention is not to withdraw the money until you retire, then you lot should budget so that you can brand regular contributions to both your 401(k) and your regular savings business relationship. Personal finance experts propose that all households proceed iii to half-dozen months of household bills in a savings account. Some people tap into their 401(k) early when they run across financial hardships. There is a tax penalty for doing so.
To decide how much you need to salve in your 401(k) account, try to get a articulate understanding of your total income during retirement. Are you eligible for a pension or some other blazon of monthly benefit? Is there a way to go a reliable gauge of the amount of social security you will receive each month? Do yous accept admission to retirement accounts with higher contribution limits?
There is no gold number for 401(thousand) savings. Instead, each person should make the best option, given their electric current upkeep and proposed future circumstances. A financial counselor is an excellent professional to help you lot decide how much you need to save from each paycheck.
Source: https://www.askmoney.com/investing/understanding-your-401k?utm_content=params%3Ao%3D1465803%26ad%3DdirN%26qo%3DserpIndex
0 Response to "No Gas at Circle K Again"
Postar um comentário